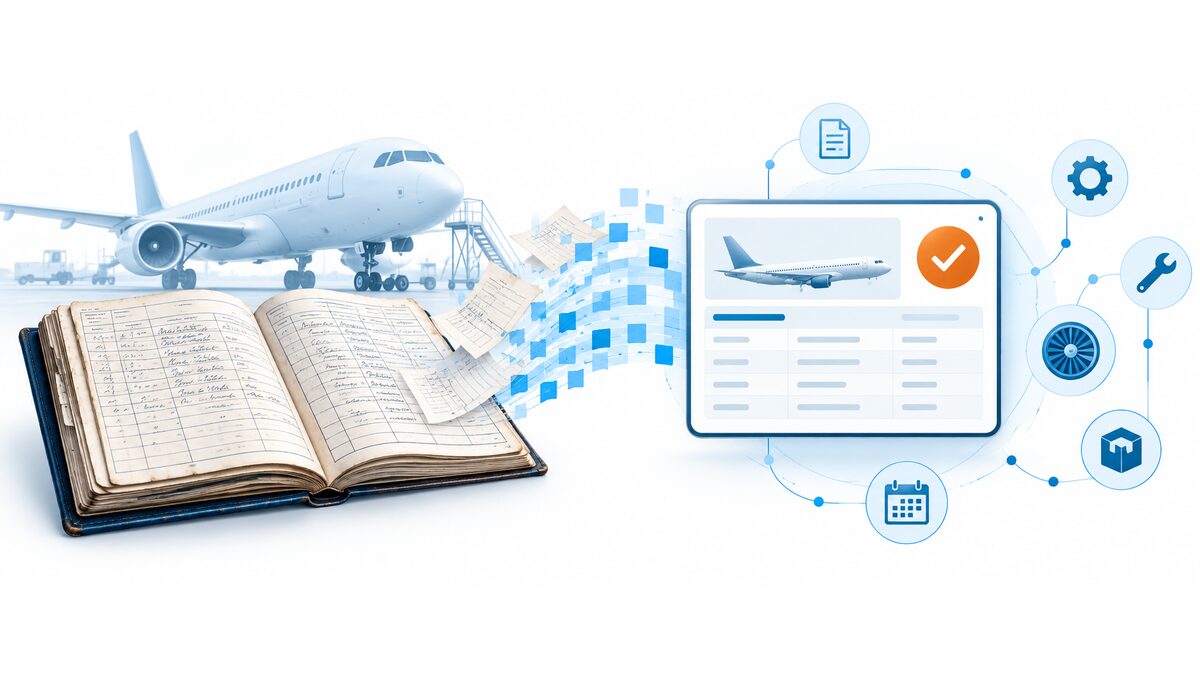
The aviation software market is valued at an estimated $12.5 billion in 2026 and is projected to reach $22.5 billion by 2033, according to Grand View Research. Spend is rising across every segment of the industry: airlines, MROs, OEMs, parts distributors, lessors and business aviation operators. The constraint is no longer vendor supply. It is fit. Operators who select software against their operational reality, their integrations and their growth plan will capture the return. Operators who select from a feature list or a generic directory will pay for capability they never use.
The market is growing faster than the fleet
Aviation software spend is compounding at roughly 8.8% a year, more than double the growth rate of the fleet it supports. Grand View Research values the market at $11.8 billion in 2025, $12.5 billion in 2026 and $22.5 billion by 2033, a compound annual growth rate of 8.8% (Grand View Research). Oliver Wyman forecasts the global commercial fleet to grow at a 3.2% CAGR, from about 30,000 aircraft in 2026 to roughly 41,000 by 2036 (Oliver Wyman, Global Fleet and MRO Market Forecast 2026-2036).
The gap between those two growth rates is the story. Operators are not buying more software because they have more aircraft. They are buying more software per aircraft, because each aircraft is older, flies more hours and carries more compliance and parts complexity than it did five years ago.
- Market sizing varies by firm. Grand View’s figures are the most cited for 2026. Other research houses publish different totals depending on scope (some include airport and air traffic management systems, others do not). Treat any single number as directional, and compare the segment you are buying in.
- MRO software is the largest slice. Grand View reports that MRO software held 34% of the market in 2025, and cloud deployment held 66% (Grand View Research).
- North America leads, Asia Pacific grows fastest. North America held a 36% revenue share in 2025. Asia Pacific is projected to post the highest growth rate through 2033 (same source).
- Total IT spend is far larger. SITA’s 2025 Air Transport IT Insights report puts total air transport technology investment at a record $50.8 billion in 2025: $36 billion from airlines (3.6% of revenue) and $14.8 billion from airports (7.3% of revenue) (Travolution, reporting SITA).
Five categories driving the growth
The fastest-moving categories map directly to the industry’s operational constraints: aging aircraft, technician supply, parts availability and data flow. Global MRO demand reached $136 billion in 2025 and is expected to approach $193 billion by the end of the decade (Oliver Wyman). The average fleet age approached 13 years in 2025. Software is how operators absorb that workload without adding headcount they cannot hire.
- AI-powered MRO and maintenance planning. BCG estimates that unavailable assets and MRO inefficiencies cost the industry roughly $27 billion in lost value a year, and that roughly half of technician time goes to non-wrench activity such as waiting for parts or searching for documentation (BCG, 2026). Digital task cards, technician AI assistants and predictive maintenance target that time directly.
- Cloud ERP and M&E systems. Cloud already holds 66% of deployments. Legacy desktop platforms are moving to browser delivery, and new cloud-native systems are competing for mid-size MROs, operators and distributors. Examples on the marketplace include Pentagon 2000, AMOS, AvSight and AirNxt.
- Supply chain visibility and parts traceability. Oliver Wyman cites raw material shortages and engine durability issues as the main drivers of longer turnaround times. Parts sales channels, traceability and back-to-birth records are now core infrastructure for distributors, lessors and MROs alike. See SmartCert, ProvenAir Technologies, Skythread and Inventory Locator Service (ILS).
- Crew management and operations control. SITA reports that 63% of airlines already use AI in operations control to manage disruption, aircraft assignment and crew availability, and 46% are upgrading flight operations systems so data is consistent in real time across flight, crew, aircraft and passenger systems (Travolution, reporting SITA).
- Flight planning and aircraft performance. Utilization reached new highs in 2025 according to Oliver Wyman. Every block hour now carries more value, which raises the return on performance and planning tools such as Automated Systems In Aircraft Performance and PACE Aerospace & IT.
What generic software directories miss
A directory lists vendors. It does not tell you which vendor fits your certificate type, your fleet, your integration stack or your region. General software marketplaces rank on reviews and keyword relevance. Aviation buyers need to filter on criteria that rarely appear in those listings.
- Operation type and segment. A Part 145 component shop, a CAMO, a cargo operator and a parts distributor buy from overlapping categories but need different workflows. An ERP built for heavy base maintenance is the wrong tool for a broker who lives in RFQs.
- Regulatory scope. Records requirements differ by authority and operation. The system must produce compliant records for the regulators you answer to (FAA, EASA, Transport Canada or others), not a generic audit log.
- Integration fit. SITA reports that 49% of airlines identify data integration and consistency as their primary barrier (Travolution, reporting SITA). Ask for proof of live connections to your parts marketplaces, accounting platform, records repository and OEM data feeds before you shortlist.
- Fleet and company size. Pricing models, implementation effort and support tiers scale very differently for a 5-aircraft charter operator and a 250-person MRO.
- Regional support. Implementation partners, time-zone coverage and data residency matter more than feature depth when the go-live team is on the other side of the world.
- Implementation model. Some vendors configure within the standard product. Others customize. The first is faster to upgrade. The second fits edge cases. Know which you are buying.
A structured, vendor-neutral selection process
The fastest way to a good decision is to define the problem before you look at a single demo. Most failed selections start with a feature comparison. Successful ones start with the operational outcome the business needs to move: turnaround time, AOG response, records audit time, quote speed or cash cycle.
- Define the outcome and the constraint. Name the metric you need to move and the cost of the status quo. Aero NextGen maps more than 150 aviation pain points to solution categories for exactly this reason.
- Map your current systems. List every system the new tool must exchange data with, and the owner of each.
- Filter on fit before features. Segment, operation type, fleet or company size, region, deployment model and integrations. This step should remove most of the market.
- Shortlist three to five vendors. Fewer and you weaken your negotiating position. More and your team loses weeks to demos.
- Run scripted demos on your own data. Give every vendor the same scenario: a real work order, a real RFQ, a real records audit.
- Validate total cost of ownership. Subscription, implementation, data migration, training, integration maintenance and upgrade cost over five years.
- Reference-check against your profile. Speak to customers with your operation type and size, not the vendor’s flagship account.
Advisory firms that specialize in aviation ERP selection, such as JETELLIGENCE and Tsunami Tsolutions, can run this process end to end for operators who do not have an internal selection team.
Where the market goes next
The next phase of aviation software is defined by data flow, not by new modules. SITA’s CEO, David Lavorel, framed it directly in the 2025 report: data coordination is limiting outcomes today (Travolution, reporting SITA). Three shifts follow from that.
- AI moves from pilot to workflow. SITA reports that 79% of airlines name generative AI and large language models as their top investment priority for the next 12 months. The return will go to operators whose records and parts data are clean enough for AI to act on.
- Consolidation continues. Oliver Wyman expects more partnerships and acquisitions between operators and maintenance providers as cost containment intensifies. Software choices made now must survive a change of ownership or a merger of systems.
- Workforce shapes the buying criteria. Oliver Wyman reports that about 41% of certified US mechanics are over 60, with about 45,000 expected to retire in the next decade. Usability and knowledge capture move from nice-to-have to selection criteria.
The Aero NextGen take
A $12.5 billion market does not need more vendors. It needs better matching. The aviation industry has a mature supply of software across every category. What it lacks is a neutral, aviation-specific way to filter that supply against the buyer’s real operation. That is the job Aero NextGen was built to do: match fleet operators, MROs, OEMs, parts distributors and lessors to vetted solution providers based on operation type, segment, size, region and integration needs, not on who bought the top ad slot.
The decision-makers who win the next five years will treat software selection as an operational decision with a measurable outcome, not an IT purchase. They will define the problem first, filter on fit, and buy what moves the metric.
“The aviation software market has never had more choice. That is exactly why selection has to start with the operation, not the feature list. Buyers who match on fit will compound the return. Buyers who buy on noise will replace the system in three years. Aero NextGen exists to make the first outcome the default.”
Monica Badra, Founder & CEO, Aero NextGen
Find your fit in 3 minutes: Complete the Solution Finder quiz and get matched to the software providers and consulting services that fit your operation, at no cost.
Sources
- Grand View Research, Aviation Software Market Size and Share Report, 2026-2033: grandviewresearch.com
- Oliver Wyman, Global Fleet and MRO Market Forecast 2026-2036 (published February 2026): oliverwyman.com
- SITA, 2025 Air Transport IT Insights, as reported by Travolution (April 2026): travolution.com
- BCG, Older Aircraft, Too Few Technicians: Why Aerospace MRO Needs a Digital Fix (2026): bcg.com